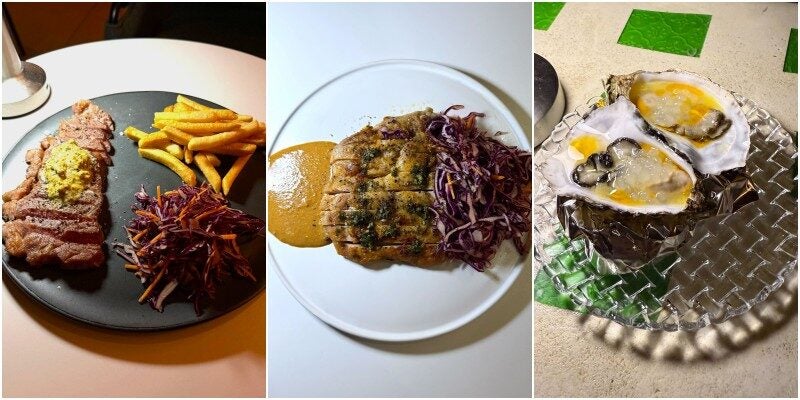
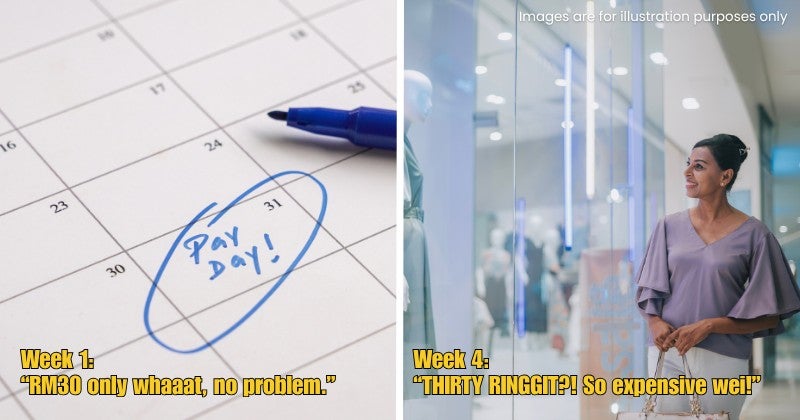
Salary just came in and suddenly that RM30 meal doesn’t seem that expensive. Add coffee? Sure. Buy the thing that’s been sitting in your cart? Okay lah, payday mah.
Fast-forward a few weeks and that same RM30 suddenly feels like a major financial decision. If this sounds familiar, you’re definitely not imagining the change in your spending habits because researchers have actually studied what happens to the way people spend around payday.
 For illustration purposes
Yes, people really do tend to spend more around payday
A 2025 study on what researchers call the “payday consumption cycle” found that household spending tended to rise around payday before dropping as people moved further into their pay cycle.
And this isn’t the first time researchers have noticed it.
Earlier research into financial behaviour around payday also found that participants generally had higher expenditure after payday than before it. Previous studies cited in the research had similarly found that overall and food spending could increase sharply around payday.
So yes, there’s evidence behind the familiar cycle of:
Week 1: “RM30 only whaaat, no problem.”
Week 4: “THIRTY RINGGIT?! So expensive wei!”
But having more money available immediately after payday is only part of the story.
Our brains don’t necessarily treat every ringgit the same way
One concept that may help explain our spending behaviour is called mental accounting.
Put simply, it describes how people mentally organise and keep track of money instead of treating every ringgit as completely interchangeable.
And it isn’t just an old theory. A large study published in 2026 involving 5,589 participants across 21 countries found that mental accounting effects remained remarkably consistent across different countries.
That can help explain why the amount sitting in our bank account can influence how comfortable a purchase feels.
Just after payday, we may mentally see plenty of room in the month’s “budget”. As that amount gets smaller and upcoming commitments remain, we may become more cautious about what we’re willing to spend.
 For illustration purposes
There may also be a ‘payday effect’ beyond simply having more cash
Interestingly, the 2025 payday study found that spending could surge around payday even among consumers who weren’t necessarily facing immediate cash shortages.
The researchers linked this pattern to factors including present bias, where we give greater weight to what we want now, as well as the mental budgets people may set for themselves each month.
Higher spending near payday could then be followed by lower spending several weeks later.
Basically, spending more at the beginning of your salary cycle can leave your future self having to compensate.
Suddenly, Week 4 you is staring at Week 1 you like:
“Was that RM30 coffee and cake really necessary?”
So, what can we actually do about it?
This doesn’t mean you shouldn’t enjoy your salary or treat yourself after getting paid.
But recognising that payday itself can affect our spending behaviour may help us make more deliberate choices.
Malaysia’s Bank Negara Malaysia includes budgeting expenditure, saving money and paying bills on time among prudent financial behaviours, while the country’s current financial literacy strategy aims to help Malaysians make more informed financial decisions.
One simple way to look at it is this: before deciding how much money you have available for payday treats, mentally separate what you’ll need for bills, necessities and savings first.
Because RM30 is still RM30 whether it’s the 1st or the 28th.
It just doesn’t always feel that way.
So, be honest: what’s the first thing you usually spend on when your salary comes in?
Also read: Did Someone Say AFFORDABLE? This Bangsar Bar Serves Steaks & Wine That Won’t Break the Bank!