News
What Malaysians May Not Realise After Repeatedly Withdrawing From EPF Account 3

Withdrawing from the Employees Provident Fund (EPF) has become much easier since Account 3, also known as Akaun Fleksibel, was introduced in May 2024. Unlike the other two accounts, it lets members withdraw their savings at any time, subject to EPF’s terms and conditions.
That access can help when you need cash for an emergency or an unexpected bill. But it also means less money saved for retirement, so here’s what you should know.
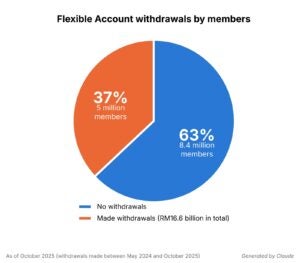
In a report, while around 8.4 million members (63%) had not made any withdrawals from their Flexible Account, a whopping 5 million members (37%) had withdrawn a total of RM16.6 billion between May 2024 and October 2025.
The report also found that:
-
4.1 million members transferred RM14.5 billion from Account 2 (Sejahtera) to Account 3 (Flexible) during the one-time transfer option in 2024.
-
81% of members who made withdrawals had less than RM500 left in their Flexible Account by October 2025.
-
6.2% had completely used up their Flexible Account savings.
1. Only 10% of new contributions go into Account 3
Following EPF’s account restructuring on 11 May 2024, only 10% of your new monthly contributions go into Account 3.
The remaining contributions are divided between the other two accounts:
- Akaun Persaraan (Account 1): Receives 75% of new contributions and is meant for long-term retirement savings.
- Akaun Sejahtera (Account 2): Receives 15% of new contributions and caters to specific needs before retirement, such as housing, education and healthcare.
- Akaun Fleksibel (Account 3): Receives 10% of new contributions and gives members access to money for short-term financial needs.
According to EPF’s official Account Restructuring Guide, this arrangement was introduced to give members greater financial flexibility while helping them maintain sufficient savings for retirement.
In other words, if you keep withdrawing from Account 3, you’re only taking money from the portion of your new contributions allocated to that account. Your Account 1 and Account 2 savings are not automatically affected.
2. You will miss out on A LOT of compound growth
Besides earning dividends on your existing savings, leaving your EPF money untouched also gives it more time to grow through something called compound growth.
According to EPF’s 2025 Dividend Announcement, both Conventional and Shariah savings received a dividend rate of 6.15% for 2025. In simple terms, compound growth means you earn dividends not only on your original savings but also on the dividends you’ve already earned.
Over time, this allows your savings to grow faster because your money is essentially earning more money for you.
For example, let’s say you have RM1,000 in your EPF account and leave it untouched for 20 years.
If your savings earn a hypothetical annual dividend rate of 6.15%, your RM1,000 could grow to approximately RM3,299.
That’s an additional RM2,299 in dividends, without you having to put in any extra money.
3. You sacrifice long-term dividend growth for short-term cash before retirement
While withdrawing from Account 3 leaves your Account 1 and Account 2 balances intact, it directly reduces the total pool of money working for your retirement.
Take two EPF members with the exact same salary and monthly contributions. One regularly withdraws from Account 3 whenever extra cash is needed, while the other leaves the account untouched.
Over time, the member who avoids withdrawals builds a substantially larger retirement fund—simply because more of their money stays invested to earn annual dividends.
This trade-off matters most when you are young. The earlier you withdraw from Account 3, the fewer years your savings have to compound.
So, should you stop withdrawing from Account 3?
Not necessarily.
Account 3 was introduced to give EPF members more financial flexibility, especially when they need money for emergencies or other immediate expenses.
There is nothing inherently wrong with withdrawing money that you are eligible to access, particularly when it is needed to cover essential expenses. However, it’s worth asking yourself whether you really need to withdraw the money or whether you can afford to leave it in your account for longer.
Would you consider withdrawing from your EPF Account 3, or would you rather leave the money untouched? Let us know in the comments!
Also Read: Budget 2027 Starts EPF at 18 — Versa Data Shows How Young M’sians Can Fuel It

What Malaysians May Not Realise After Repeatedly Withdrawing From EPF Account 3
Withdrawing from the Employees Provident Fund (EPF) has become much easier since Account 3, also known as Akaun Fleksibel, was...

Here’s the Complete List of Housing Developers BLACKLISTED by the Housing Ministry
Buying a house is one of the biggest financial commitments you’ll make, but what if the developer behind your dream...

Dentist Fined RM70k for Letting SPM-Level Staff Perform Dental Scan While She Had Lunch
A dentist has been found guilty of employing an unregistered dental practitioner and allowing the individual to perform dental procedures...

Malaysians May Have to Serve 180 Days of PLKN Instead of 45 Days
Malaysians could potentially spend up to 180 days in the National Service Training Programme (PLKN) in the future, following a...

Prabowo Apologises to M’sia & S’pore Over Haze, Pledges Crackdown on Companies Behind Forest Fires
Following the transboundary haze caused by forest and land fires in Indonesia, President Prabowo Subianto has issued an apology to...

Experts: Even If Hackers Attack Banks, M’sians’ Outstanding Loans Won’t Simply Disappear
Professor Dr Zubaile Abdullah, a senior researcher at the Centre for Cybersecurity and Data Intelligence (CCDI), Universiti Tun Hussein Onn...

NACSA Confirms Global Microsoft 365 Outage is Not a Cyberattack, Urges M’sian Agencies to Stay Vigilant
Following the massive global Microsoft 365 outage that disrupted productivity tools like Outlook and Teams for tens of thousands of...

Best Work Perk Ever? Logitech Gives 7,000 Employees A Day Off for First-Ever Gaming Day Ahead of GTA VI Release
Logitech is making headlines after announcing its first-ever company-wide gaming day on 19 November, giving employees a dedicated day off...

One Layer, Two Climates: 5 Ways UNIQLO HEATTECH Suits Both Winter Holidays & Daily Life in M’sia
For many Malaysians, the year-end holidays are a chance to cuti-cuti somewhere colder and trade the tropical heat for a...

Talentbank Career Passport Guides Students From University to Industry Job at 9th Graduates’ Choice Award
The Ministry of Higher Education (KPT), public and private universities, a wide range of business associations and chambers, and Talentbank...

Malaysia’s First “VS CHALLENGE” is Coming to Kuala Lumpur – Are You Ready for the Challenge?
Get ready to move, compete and challenge yourself as VS CHALLENGE, an action-packed entertainment concept from Japan produced by Bandai...
Here’s the Complete List of Housing Developers BLACKLISTED by the Housing Ministry

“Malaysia belongs to China” Says Chinese Woman After Asking Malaysians to Pay for Their Food
Malaysians May Have to Serve 180 Days of PLKN Instead of 45 Days

M’sian Raises Concern After KL Bus Stop Allegedly Turns Into Shelter for Foreign Nationals, Urges DBKL to Act

Aged 52 to 64, These Malaysian Gamers Are Crowned Asia’s FIRST Senior Esports Champions



-
News6 hours ago
Here’s the Complete List of Housing Developers BLACKLISTED by the Housing Ministry
-
News21 hours ago
Dentist Fined RM70k for Letting SPM-Level Staff Perform Dental Scan While She Had Lunch
-
 Social Stories20 hours ago
Adam’s Family & The ‘Lady In Red’ Controversy: Here’s What We Know So Far
-
 Social Stories3 hours ago
A Malaysian Uncle Made a Game That Lets You Run Your Own Kopitiam!